
What a neural association does and does not identify
A participant chooses between accepting and rejecting a monetary gamble while researchers observe blood-oxygen-level-dependent activity in the brain. Certain regions show activity related to the magnitude of possible losses. It is tempting to turn that finding into a product claim: the region lights up, therefore the person is afraid of losing money. The inference is not justified. The signal is a statistical association measured under specific instructions and timing, not a direct reading of private emotion. The research question is whether evidence from neural loss-aversion tasks can identify fear in an individual trader and whether that identification would mean anything for future market decisions.
Tom and colleagues studied neural correlates of loss aversion during decisions involving possible monetary gains and losses [1]. Their experiment provided evidence about how potential outcomes related to brain activation and differences in risk preference in a controlled laboratory paradigm. It did not measure a trader's live gold orders, transaction costs or realized profitability. A common error is to take a result that helps explain a population-level experimental pattern and treat it as an individual diagnostic instrument. The leap requires new validation and an explicitly defined target, neither of which can be supplied by an appealing image of brain activation.
De Martino and colleagues examined the framing effect and its neural associations during risky decisions [2]. The same monetary options can be perceived differently depending on presentation. This complicates a simple fear interpretation: an observed neural contrast may reflect framing, appraisal, task engagement or a combination. Brain regions participate in many processes rather than representing one psychological construct exclusively. Even where an experimental manipulation influences average responses, that does not establish a unique fingerprint for one person's subjective state. Both the behavioral choice and the neural measurement require context. The Colored Brain Cluster Problem: False Positives in fMRI examines statistical inference in neuroimaging. The present issue comes afterward: even a well-supported group difference needs a valid psychological interpretation. A signal can be reproducible without being specific to fear, and specific to a task without forecasting financial outcomes. NSI should distinguish the observed BOLD signal, the investigator's hypothesized construct and the behavioral outcome used to evaluate the hypothesis. Collapsing those levels would make a model appear more certain than the underlying evidence supports.
Why decoding does not automatically become diagnosis
Yarkoni and colleagues developed and evaluated a large-scale synthesis approach for mapping neural and cognitive information [3]. Their work shows why broad databases and explicit decoding methods are preferable to assuming that activity in one region means one mental state. But even a successful classifier relies on its training conditions, category definitions and evaluated sample. A statistical mapping is not an unrestricted mind reader. Accuracy on a neuroimaging research dataset cannot be transported into consumer trading without independent evidence that the same constructs and measurements remain valid. For individual interpretation, investigators must specify what fear would mean in an operational protocol. Is it self-reported anxiety, avoidance of a loss-bearing gamble, physiological arousal, startle response or withdrawal from risk after a negative outcome? These outcomes can diverge. A participant may report concern while making a deliberate rational decision, or remain outwardly calm while taking an excessive risk. Valid measurement would compare multiple indicators across repeated situations, estimate their disagreement and test reliability rather than assigning one emotional label to an activation map.
A research design should separate acquisition from evaluation. Data collected while researchers define regions, optimize preprocessing or choose a threshold cannot also serve as untouched confirmation. The study would need a preregistered decoding task, participant-level splits, preferably an independent cohort, and reporting of false positives as well as average performance. Models should be compared against simple baselines using only variables available at the intended moment. If the goal is forecasting trading behavior, the outcome must be defined separately from the brain features. Otherwise apparent accuracy can arise from task labels leaking into the model. Time is another confound. An fMRI response has a hemodynamic time course and involves controlled experimental timing. A rapid gold-price change unfolds at a different temporal scale and in a different environment. Aligning a delayed hemodynamic signal with a tick-by-tick price chart could create seductive but misleading patterns. Study designers should specify lag assumptions before testing and include controls for stimulus timing, motion and task difficulty. A neural association with possible financial losses does not identify whether a market price will subsequently rise or fall.
A falsifiable neurofinance research program
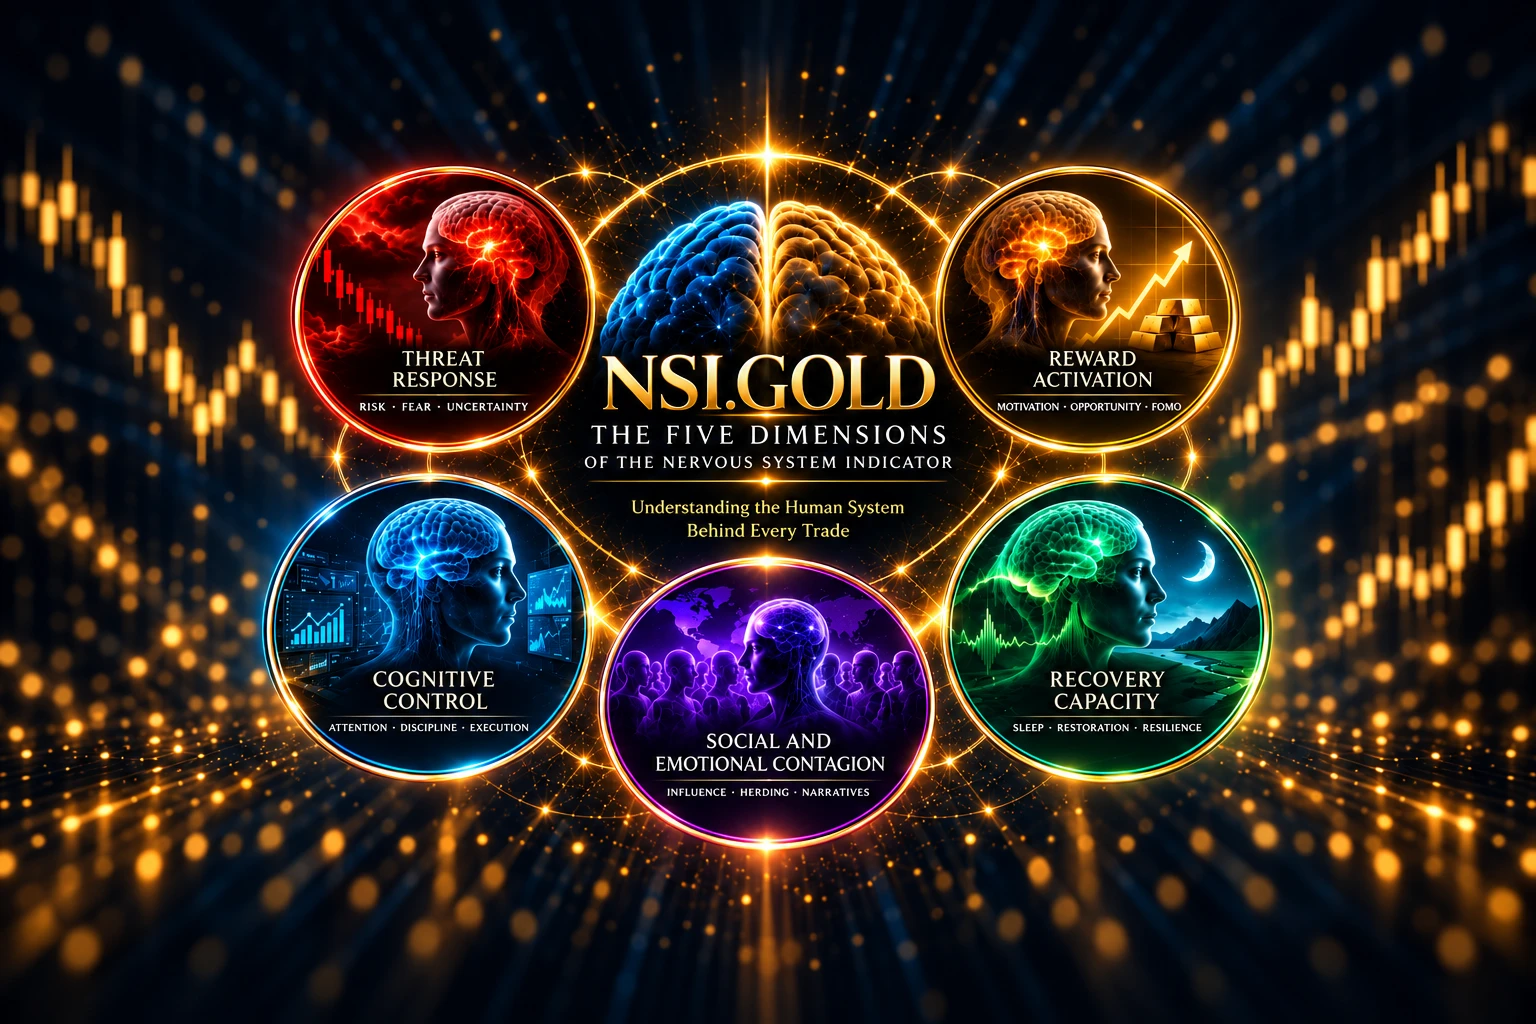
An appropriate NSI protocol would begin with transparent constructs and modest questions. First ask whether a predefined neural measure differentiates specified experimental conditions in a representative sample. Then test whether the measure adds explanatory value beyond choices and self-reports in unseen participants. Only after replication could researchers investigate whether anything transfers to real-world decision quality, and even then the target would be behavioral consistency rather than direction of XAU/USD. What Does NSI Measure? Construct Validity Before Composite Scores provides the vocabulary for separating measures from proposed labels. Researchers must disclose population and environment. A handful of highly trained institutional traders, a student laboratory sample and an online group of retail traders are not interchangeable. Can a Small Trading-Floor Study Generalize to Thousands of Gold Traders? addresses the transport problem. Importantly, no positive result in a small sample would license a product to claim universal fear detection. Even a dependable association may have no useful effect on the quality of decisions or the financial outcome of a trading strategy.
The conclusion is a boundary rather than a dismissal of neuroscience. Neural measurements can contribute to explanations of risky choice under carefully controlled circumstances. They cannot be treated as direct labels of fear or as shortcuts to financial prediction. Experimental contrasts, distributed brain processes, measurement reliability and independent generalization tests all matter. NSI is a proposed interdisciplinary framework, not a clinically validated neurodiagnostic method and not a financially validated system for forecasting gold. Its scientifically defensible work is to formulate testable constructs and publish the limits of the evidence alongside the findings.
Scientific bibliography & sources
- [1] Tom SM et al. The neural basis of loss aversion in decision-making under risk. Science (2007). https://pubmed.ncbi.nlm.nih.gov/17255512/
- [2] De Martino B et al. Frames, biases, and rational decision-making in the human brain. Science (2006). https://pubmed.ncbi.nlm.nih.gov/16888142/
- [3] Yarkoni T et al. Large-scale automated synthesis of human functional neuroimaging data. Nature Methods (2011). https://www.nature.com/articles/nmeth.1635
Research note
NSI is a proposed research framework, not an independently validated medical or financial prediction system. This article is research and education, not individualized medical or investment advice. Market observations are timestamped historical context, not live prices.
 Research
 Research
 Research